What Is This Article About?
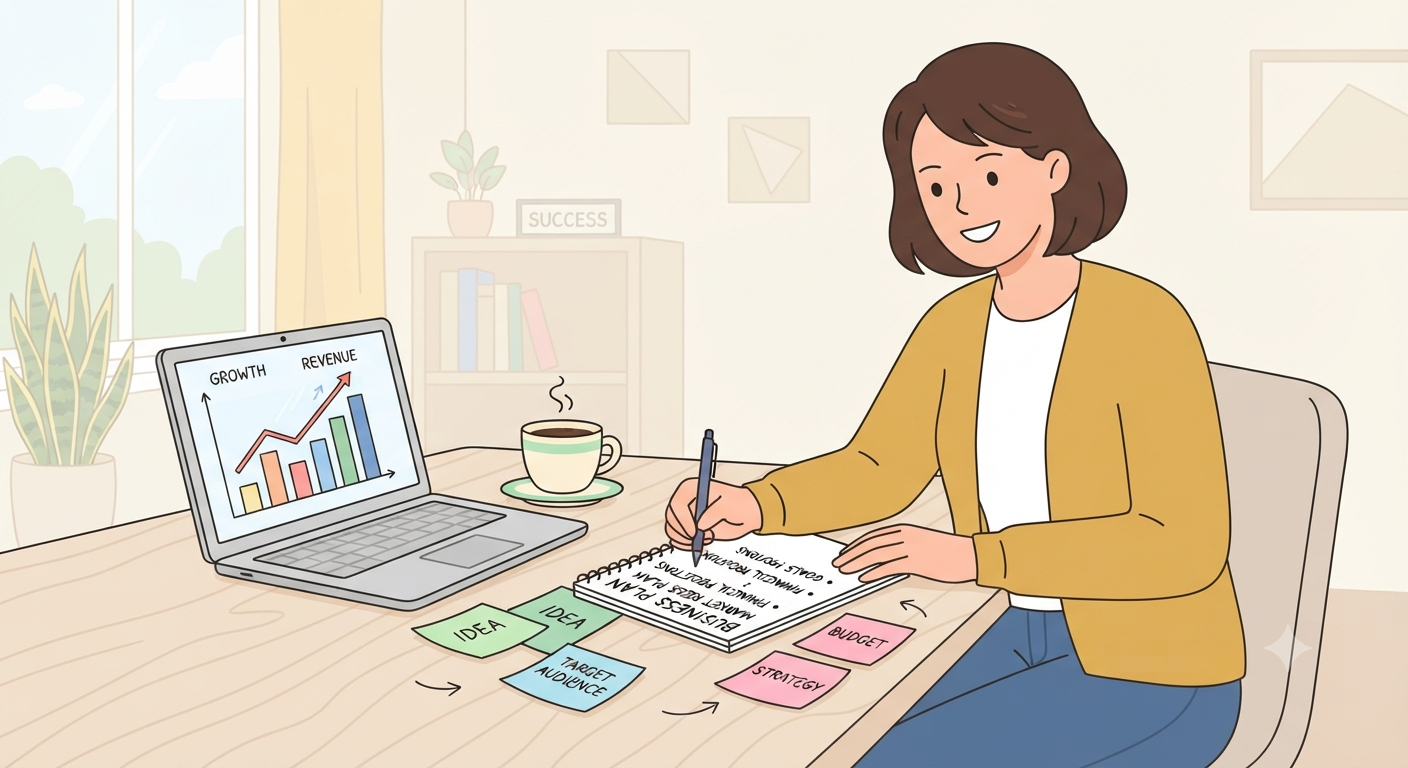
A simple business plan helps you turn a business idea into a clear, practical roadmap. It explains what your business will offer, who your customers will be, how you will attract them, how much money you will need, and how you expect to generate revenue and profit. Whether you are starting a small local business, launching an online venture, or expanding an existing company, a well-organized business plan can help you make informed decisions and reduce avoidable risks. This guide breaks the process into 10 manageable steps, with five practical actions under each step. You do not need an MBA or advanced financial knowledge to begin. You need a realistic idea, basic research, honest calculations, and a willingness to review your plan as your business develops.
The 10-Step Guide to Writing a Simple Business Plan
Define Your Business Idea and Objectives

The first step in writing a business plan is to describe exactly what your business will do and what you want to achieve. A business idea becomes more useful when you can explain the problem it solves, the customers it serves, and the value it provides. Your objectives give the business a clear direction and help you measure progress. Before investing money or making major commitments, make sure you can explain your business idea in a few straightforward sentences.
- Describe your business idea: Write a brief explanation of the product or service you intend to sell and the problem it solves.
- Identify the customer need: Explain why people would want your product or service and what benefit they would receive.
- Set clear business objectives: Decide what you want to achieve in the first 6 or 12 months, such as acquiring 50 customers or reaching a specific monthly revenue target.
- Choose your business model: Determine whether you will earn money through product sales, service fees, subscriptions, commissions, or another method.
- Define your long-term vision: Describe what you want the business to become over the next three to five years.
Research Your Target Market

Market research helps you understand whether sufficient demand exists for your business idea. Instead of assuming that people will buy your product or service, investigate their needs, purchasing habits, budgets, and existing alternatives. You do not necessarily need expensive research reports. Conversations with potential customers, competitor websites, online reviews, and publicly available industry information can provide useful initial insights.
- Define your target audience: Identify the people or businesses most likely to purchase your offer, considering location, age group, occupation, business size, or budget where relevant.
- Understand customer problems: Find out what your prospective customers struggle with and which solutions they currently use.
- Estimate market demand: Investigate how frequently customers need your product or service and how much they may be willing to pay.
- Study customer purchasing behavior: Determine where customers look for solutions, how they compare alternatives, and what influences their buying decisions.
- Validate your assumptions: Interview potential customers, conduct a small survey, or test a basic offer before making a large investment.
Analyze Your Competitors

Competitor analysis helps you understand what other businesses already offer and how your proposed business can stand out. Competitors may include direct alternatives selling the same products or indirect alternatives that solve the same customer problem in a different way. The objective is not necessarily to offer the lowest price. You may be able to compete through better service, convenience, specialization, quality, reliability, or a more suitable customer experience.
- Identify direct competitors: List businesses selling similar products or services to the same target audience.
- Examine indirect competitors: Identify alternative solutions customers could choose instead of your offer.
- Compare prices and services: Review competitors’ pricing, product features, service quality, delivery options, and customer support.
- Study customer reviews: Look for recurring complaints, unmet expectations, and positive features customers appreciate.
- Define your competitive advantage: Identify one or two meaningful reasons customers might prefer your business.
Define Your Products or Services

Your business plan should explain what you intend to sell and why your offer is valuable to customers. A clear product or service description helps you estimate costs, establish prices, plan operations, and communicate your value proposition. For a new business, begin with a manageable range of offerings rather than launching too many products or services at once. A focused initial offer makes it easier to test demand, control expenses, and learn from customers.
- Describe your main offer: Explain the key features, benefits, quality standards, or service outcomes customers can expect.
- Identify your unique selling proposition (USP): State what makes your offer meaningfully different or more suitable for your target customers.
- Choose your initial product range: Select the products or services you can deliver reliably with your available resources.
- Plan sourcing and delivery: Identify suppliers, materials, equipment, staff, or technical resources required to provide your offer.
- Consider future improvements: List possible additional products, service upgrades, or features you may introduce after validating demand.
Create a Marketing and Sales Strategy

A business plan should explain how you will attract potential customers, convert their interest into purchases, and build lasting customer relationships. Even a good product may struggle if customers do not know it exists or cannot understand its benefits. Your marketing and sales strategy should match your target audience, available budget, and business model. Start with a few suitable marketing channels and measure which ones produce genuine enquiries and sales.
- Choose your marketing channels: Decide whether you will use search engines, social media, email marketing, local networking, referrals, marketplaces, or direct sales.
- Develop your brand identity: Establish a suitable business name, logo, brand message, and consistent presentation that customers can recognize.
- Plan your promotional activities: Create a monthly content calendar, introductory campaigns, demonstrations, or other relevant promotional activities.
- Establish a sales process: Decide how customers will enquire, receive information, compare options, place orders, make payments, and receive their purchases.
- Set a marketing budget: Estimate your monthly promotional expenditure and track the number of enquiries, conversions, and customers generated.
Plan Your Business Operations

Business operations include the everyday activities required to deliver products or services consistently. Your plan should identify where the business will operate, what resources it needs, who will perform important tasks, and how customers will receive their orders or services. Operational planning is particularly important for small businesses because limited staff, cash, and equipment can restrict growth. A straightforward operating system helps reduce delays, unnecessary expenses, and service inconsistencies.
- Choose your operating location: Decide whether you will operate from home, a rented shop, an office, a workshop, or an online platform.
- List essential resources: Identify the equipment, software, inventory, raw materials, utilities, and other resources you need to begin.
- Identify suppliers and partners: Research reliable suppliers, manufacturers, distributors, delivery providers, or professional service partners.
- Allocate responsibilities: Decide which activities you will handle yourself and which require employees, freelancers, or external service providers.
- Establish daily procedures: Plan how you will manage orders, customer enquiries, inventory, payments, quality checks, and complaints.
Calculate Your Startup Costs and Funding Requirements

Before launching your business, estimate how much money you need to establish it and keep it operating until revenue becomes sufficient. Many businesses encounter financial difficulties not because the idea is poor, but because the initial budget overlooks important expenses or the time needed to generate sales. Your startup budget should distinguish one-time setup costs from recurring operating expenses. You should also identify how you will finance the business without putting more money at risk than you can reasonably afford.
- List one-time startup expenses: Include equipment, registration, initial inventory, website development, deposits, furniture, and other setup costs where applicable.
- Estimate monthly operating expenses: Calculate expected rent, salaries, utilities, software subscriptions, marketing, transportation, and other recurring expenses.
- Calculate working capital: Estimate the cash required to cover operating expenses while waiting for customers to pay and sales to become consistent.
- Identify funding sources: Determine how much you can contribute personally and whether you may need a loan, investor, business partner, or other legitimate funding source.
- Add a contingency allowance: Include a reasonable reserve for unexpected expenses, delays, and cost increases.
Prepare Your Revenue, Expense, and Profit Forecast

Financial forecasting helps you determine whether your business model has a realistic chance of becoming profitable. Your business plan should show how much you expect to sell, what it will cost to generate those sales, and how much money may remain after expenses. You do not need complicated accounting software to create an initial forecast. A spreadsheet containing realistic assumptions about sales volume, pricing, direct costs, and monthly expenses is sufficient to begin. Remember that revenue, profit, and cash flow are different measures.
- Estimate monthly sales revenue: Calculate expected sales using the number of units you expect to sell multiplied by the average selling price. For example, selling 200 units at ₹500 each produces ₹1,00,000 in monthly revenue.
- Calculate direct costs: Estimate the costs directly associated with producing or delivering the products or services you sell.
- Estimate operating expenses: Include rent, salaries, marketing, utilities, software, administration, and other relevant expenses.
- Calculate expected profit: Subtract direct costs and operating expenses from revenue, while accounting separately for interest, taxes, depreciation, and other applicable items where necessary.
- Prepare different scenarios: Estimate conservative, expected, and optimistic outcomes to understand how changes in sales volume, costs, or prices may affect profitability.
Set Business Goals and Create an Action Plan

A business plan becomes useful when it translates your ideas into specific activities, deadlines, and measurable results. Without clear goals, you may spend time on tasks that feel productive but do not contribute meaningfully to business growth. Your action plan should prioritize essential activities and assign responsibility for completing them. For a small business, a simple 30-, 60-, and 90-day plan can provide enough structure to get started and review progress regularly.
- Set measurable goals: Establish specific targets for sales, customers, revenue, customer retention, or other relevant business outcomes.
- Break goals into smaller tasks: Divide each target into manageable activities, such as researching suppliers, developing a website, or contacting potential customers.
- Set realistic deadlines: Assign completion dates based on your budget, available time, resources, and dependencies between tasks.
- Assign responsibilities: Identify who is accountable for each task and what resources are required to complete it.
- Track progress regularly: Review completed tasks, missed deadlines, expenses, and performance against your targets.
Review, Improve, and Update Your Business Plan

A business plan is not a document you write once and forget. Actual customer demand, competitor activity, operating costs, and market conditions may differ from your original assumptions. Regular reviews help you identify these differences and make informed adjustments. You do not need to rewrite the entire plan whenever circumstances change. Focus on the sections affected by new information and keep your financial forecasts, goals, and operating assumptions up to date.
- Compare actual results with forecasts: Review monthly revenue, expenses, sales volume, and profit against your original estimates.
- Collect customer feedback: Identify recurring complaints, unmet needs, and suggestions that could improve your offer.
- Evaluate marketing effectiveness: Determine which promotional activities generate profitable sales and which consume resources without sufficient results.
- Identify emerging risks and opportunities: Monitor changing customer preferences, supplier problems, new competitors, and opportunities for expansion.
- Update your priorities: Revise your financial projections, business goals, and action plan according to what the results reveal.
Practical Tips for Writing a Simple Business Plan
- Keep it concise: Focus on information needed to understand, launch, and manage your business.
- Use realistic assumptions: Base sales estimates, expenses, and customer demand on research rather than optimism alone.
- Start with a simple format: A word-processing document or spreadsheet is sufficient for an initial business plan.
- Understand your customers: Direct conversations can reveal problems and opportunities that desk research may miss.
- Track profit, not just revenue: High sales do not necessarily mean that a business is financially healthy.
- Plan for cash flow: Consider when you will receive payments and when you must pay suppliers, employees, rent, and other expenses.
- Identify major risks: Consider low sales, rising costs, supplier delays, competition, and unexpected operating problems.
- Avoid unnecessary spending: Test your business idea on a small scale before committing substantial capital.
- Use measurable goals: Give each important objective a target and a deadline.
- Review the plan regularly: Update it as your business gains customers and generates real financial data.
Conclusion
Writing a simple business plan does not require advanced business qualifications or complicated financial models. It requires a clear understanding of your business idea, target market, competitors, products or services, marketing strategy, operations, funding requirements, and financial projections.
The 10 steps in this guide provide a practical framework for turning a business idea into an actionable plan. Start by understanding your customers and validating demand. Then calculate the costs, estimate potential revenue and profit, and establish measurable goals.
The most important principle is to build your business plan around evidence rather than assumptions. Begin with a manageable plan, test your ideas in the real market, monitor your results, and make improvements as you learn. A realistic, regularly updated business plan can help you make better decisions and build a more sustainable business.
Frequently Asked Questions (FAQs): How to Write a Simple Business Plan
What is a simple business plan?
A simple business plan is a short document that explains your business idea, target customers, products or services, marketing strategy, financial requirements, and goals. It helps you organize your ideas and create a practical roadmap for starting and growing your business.
How do I write a business plan in 10 steps?
To write a business plan in 10 steps, define your business idea, research your market, identify your target customers, analyze competitors, describe your products or services, develop a marketing strategy, plan operations, estimate startup costs, prepare financial projections, and set measurable business goals.
Can I write a business plan without business experience?
Yes. You can write a business plan without previous business experience by researching your industry, understanding your customers, estimating your expenses, and setting realistic goals. Start with a simple format and improve it as you learn more about your market.
What are the main components of a business plan?
The main components of a business plan typically include an executive summary, business description, market research, target audience, competitor analysis, product or service details, marketing and sales strategy, operational plan, financial projections, and business goals.
How long should a simple business plan be?
A simple business plan can be approximately 3–10 pages, depending on the complexity of your business. A plan for your own use may be shorter, while a plan prepared for investors or lenders may require more detailed market research and financial information.
Do I need a business plan to start a small business?
A business plan is not always legally required to start a small business, but it is useful for making informed decisions. It helps you estimate costs, identify customers, manage risks, and understand how your business can generate revenue and become profitable.
How do I calculate the startup costs for my business plan?
Calculate startup costs by listing one-time expenses such as equipment, registration, furniture, website development, and initial inventory. Then estimate recurring expenses such as rent, salaries, utilities, marketing, and software. Include working capital for unexpected expenses and the initial period of operation.
What financial information should a business plan include?
A business plan should generally include estimated startup costs, revenue forecasts, operating expenses, cash flow projections, and expected profit or loss. These estimates help you assess whether your business model is financially viable and how much funding you may need.
Can I write a business plan using AI tools?
Yes. AI tools can help you organize your business ideas, create a business plan outline, draft sections, and identify questions that need further research. However, you should verify market data, check financial assumptions, and customize the plan to reflect your actual business, customers, and resources.
How often should I update my business plan?
Review your business plan at least every three to six months, or whenever there is a significant change in your business. Update your sales figures, expenses, customer needs, marketing strategy, and financial projections based on actual performance and changing market conditions.